Bitcoin’s volatility has plunged, but extreme price swings are more frequent than in 2018
CoinDesk analysis finds 10 unusually large trading days in 2026, raising questions about how investors measure risk in an increasingly institutional crypto market.
Make preferred on
Share this article
Summary
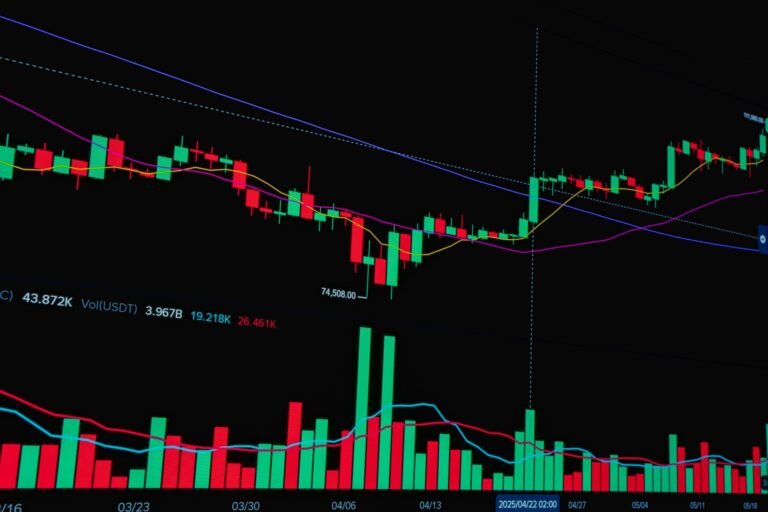
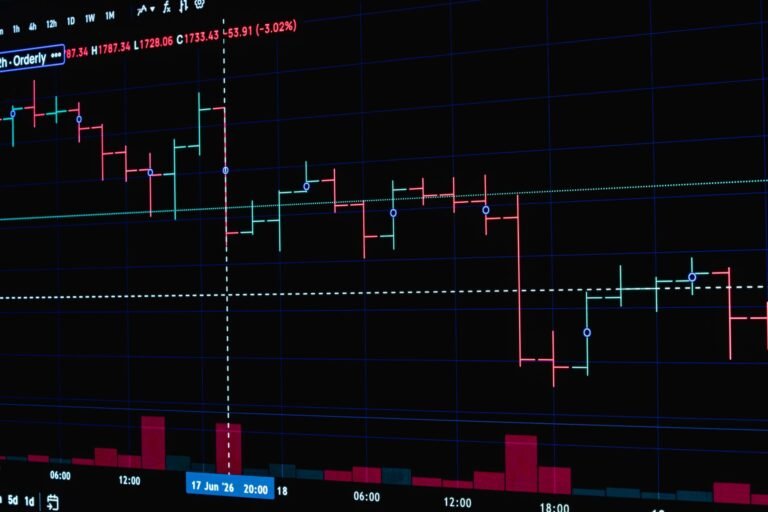
- Bitcoin has recorded 10 three-sigma trading days in 2026, exceeding the eight seen during the 2018 bear market, even as its annualized volatility has fallen to about 46% from 84%.
- The frequency of extreme moves suggests that standard value-at-risk models, which rely heavily on recent volatility, may understate bitcoin’s tail risk and encourage overly large portfolio allocations.
- Macroeconomic shocks and crowded derivatives trades can amplify sudden price swings, though deeper liquidity, stronger risk management and greater institutional participation have helped the market absorb them.